-
An accounting review recommends that Apapa Boat Club’s Commodore, Uwem Whyte, refund approximately ₦11.35 million.
-
The report questions spending, transactions involving businesses linked to officials and weaknesses in financial controls.
-
Whyte and Membership Secretary Ikem Chris Okeke say the committee did not authorise the exercise and dispute its process.
-
Who commissioned the review remains unclear, while its disputed findings require further verification.
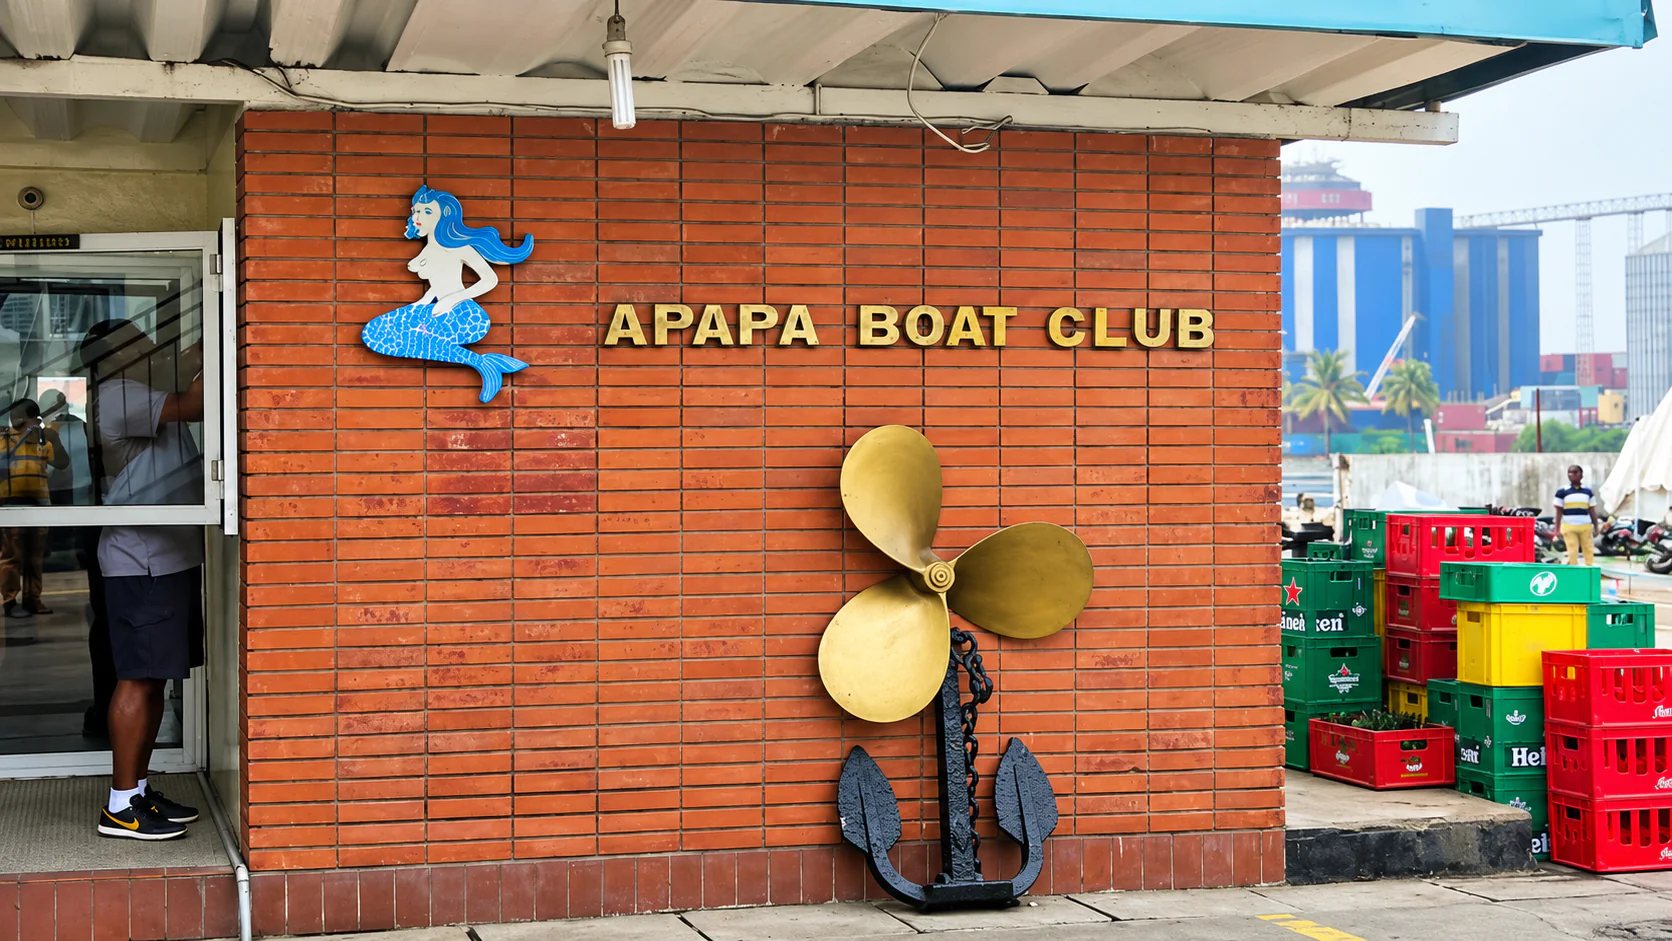
October 25, (THEWILL) – An accounting review recommending that Apapa Boat Club’s Commodore, Uwem Whyte, refund approximately ₦11.35 million has become the subject of an authorisation dispute, with Whyte and Membership Secretary Ikem Chris Okeke saying the club’s committee did not sanction the exercise.
The report, dated October 8, 2026, questions transactions involving businesses it associates with the two officials and identifies weaknesses in procurement, accounting systems and expenditure oversight. However, who commissioned the review—and the authority under which it was conducted—remains unestablished in the documents examined by THEWILL.
Prepared on Shofolawe-Bakare & Co.’s letterhead, addressed to the Honorary Treasurer and signed by Joseph Ahonsi, the document describes itself as a review of the club’s accounting and internal control system for January 2025 to August 2026. Although the exercise was described as a “forensic audit” during THEWILL’s interview, that is not the engagement description used in the report. Its findings are now in dispute.
Speaking to THEWILL, Whyte challenged both the exercise’s authorisation and the circulation of its findings.
“The committee should be informed if an audit is conducted. Don’t you think so?” he asked.
He subsequently said the exercise was undertaken without committee instruction and alleged that the completed report was not given to the trustees or committee.
“The auditor did not ask any question,” Whyte said.
Okeke also disputed the process. “The man who did an audit did not contact anybody,” he told THEWILL. Asked whether the committee sanctioned it, he answered: “No. And the committee is taking legal action.”
The materials supplied to THEWILL do not include court filings establishing the nature or status of that reported legal action. The statements represent the accounts of the two interviewed officials, rather than independently verified positions of every committee member.
THEWILL made repeated telephone calls to Mr Tokunbo Shofolawe-Bakare, identified as the firm’s founder, seeking his response and clarification on who commissioned the examination of the club’s financial records. The calls went unanswered.
A woman who identified herself only as Mrs Lawal and said she worked with Mr Shofolawe-Bakare told THEWILL that Shofolawe-Bakare & Co. carried out the club’s financial audit.
Her account supports the firm’s involvement but does not establish who commissioned the exercise and whether it was authorised.
The financial concerns centre on transactions the reviewer describes as involving related parties and awarded without competitive bidding.
Appendix 3 lists ₦112,034,452 across five businesses the report associates with Whyte: Leaf Green Harvest Ventures, Tunbridge Flex Projects, Liquid Associates, Poslini International and Tipple and Sip.
The schedules include goods and services recorded as supplied, ₦8,617,864 in unpaid Leaf Green invoices and Tunbridge transactions before a separately listed ₦1.5 million refund.
Company-search documents supplied with the review record Uwem Ataudo Whyte as holding 60 per cent of Leaf Green and 90 per cent of Tunbridge, and as the sole proprietor of Tipple and Sip. These records support business connections requiring scrutiny of disclosures and approvals.
Appendix 9 separately lists ₦21,097,300 involving Auto Alternative Nigeria Limited and Christopher Okeke. It comprises ₦17,846,500 under Auto Alternative and ₦3,250,800 under Okeke’s name, including tiles and road signage. The corresponding search lists “Okeke Christopher I.” as an Auto Alternative director.
The refund recommendation concerns a narrower set of disputed charges. The reviewer attributes ₦4,818,733.75 in entertainment expenditure to Whyte, questions a ₦2,398,110 processing fee for software it says was sponsored, and recommends recovery of ₦4,150,000 paid for maintenance of software described as inoperative amongst others.
Beyond procurement, the reviewer reports inadequate project budgeting, overlapping purchasing and stock-control responsibilities, and difficulties generating accounting reports and reconciling receipts through members’ payment applications.
There is also a material conflict over consultation. While Whyte said the reviewer asked no questions, pages five and six of the report describe discussions involving the Commodore, the reviewer, the general manager and an application consultant about accounting software. Those accounts require clarification; the supplied materials do not independently establish which is accurate.
An accompanying law-firm letter indicates that Ahonsi instructed corporate searches. It does not identify who commissioned the wider accounting review.
The report recommends that Whyte and Okeke step aside and proposes offsetting unpaid Leaf Green bills against the recommended refund.
The central unanswered questions remain who authorised the review and how the indicted officials and suppliers respond to the findings.