-
The CBN’s 350-basis-point rate cut could lower funding costs, but borrowers may have to wait before cheaper credit reaches them.
-
T-bill and bond yields have already fallen sharply, raising questions about returns for fixed-income investors as monetary conditions ease.
-
Banks, businesses and investors face different effects as lower rates reshape credit demand, interest margins and the relative appeal of fixed income and equities.
September 28, (THEWILL) – The Central Bank of Nigeria’s decision to cut the Monetary Policy Rate (MPR) from 26.5 percent to 23 percent is one of the biggest monetary-policy shifts in recent years.
The 350-basis-point reduction lowers the benchmark cost of money, but its impact on the wider economy will depend on how quickly it passes through banks, financial markets and businesses.
The Monetary Policy Committee also retained the Cash Reserve Ratio for deposit money banks at 45 percent and recalibrated the standing facilities corridor to +50/-300 basis points around the new MPR.
Here are six areas where the rate cut could have an impact.
-
Borrowing Costs: Will Bank Lending Rates Actually Fall?
The immediate question for businesses and households is whether the 23 percent MPR will translate into cheaper bank loans.
The average maximum lending rate fell to 33.16 percent in June 2026 from 34.78 percent in May, according to CBN data. However, it was still well above the 29.51 percent recorded in June 2025.
This shows why a lower MPR does not automatically produce an equivalent reduction in lending rates. Banks price loans based on several factors, including their cost of funds, credit risk, operating costs, liquidity conditions, and expected returns.
The 350-basis-point cut therefore creates room for lending rates to fall, but the speed and size of the pass-through will depend on those other factors.
-
Fixed Income: Could T-Bill And Bond Returns Fall Further?
Fixed-income investors have already seen yields decline ahead of the latest MPC decision.
The 364-day Treasury bill stop rate fell to 15.89 percent on September 23, while the 91-day and 182-day bills stopped at 15.50 percent and 15.80 percent, respectively.
FGN bond yields have also moved lower. On September 25, selected benchmark bonds were trading around 15.6–16 percent, compared with yields above 17 percent earlier in September.
That means investors buying new fixed-income instruments could face lower returns if yields continue adjusting downward.
For existing bondholders, however, falling yields can increase the market value of securities already held, creating potential capital gains for investors who sell before maturity.
READ ALSO:
-
Bank Earnings: Will Lower Rates Squeeze Interest Income?
Banks are particularly exposed to the rate cycle because interest income and funding costs are central to their earnings.
First HoldCo’s H1 2026 results illustrate the issue. Interest income fell 2.7 percent year-on-year to ₦1.40 trillion, while net interest income declined 2.8 percent to ₦879.1 billion. Its net interest margin stood at 9.5 percent, while cost of funds was 4.3 percent.
A sustained decline in market rates could put pressure on yields earned on loans and investments. At the same time, banks could benefit if their own funding costs, particularly deposit and wholesale funding costs, decline.
The other side of the equation is loan growth. If cheaper money generates stronger demand for credit, higher lending volumes could partly offset lower margins.
-
Private-Sector Credit: Will Cheaper Money Increase Borrowing?
The ultimate test of monetary easing is whether more money reaches businesses and households.
Private-sector credit increased to ₦83.26 trillion in June 2026 from ₦81.04 trillion in May, representing a monthly increase of ₦2.22 trillion and roughly 9 percent growth year-on-year. More recent data put private-sector credit at ₦84.55 trillion in August.
The rate cut could accelerate that expansion if banks become more willing to lend and borrowers find financing more affordable.
But demand will also matter. Businesses may remain cautious if they face weak consumer demand, high operating costs, or uncertainty over future inflation and exchange rates.
-
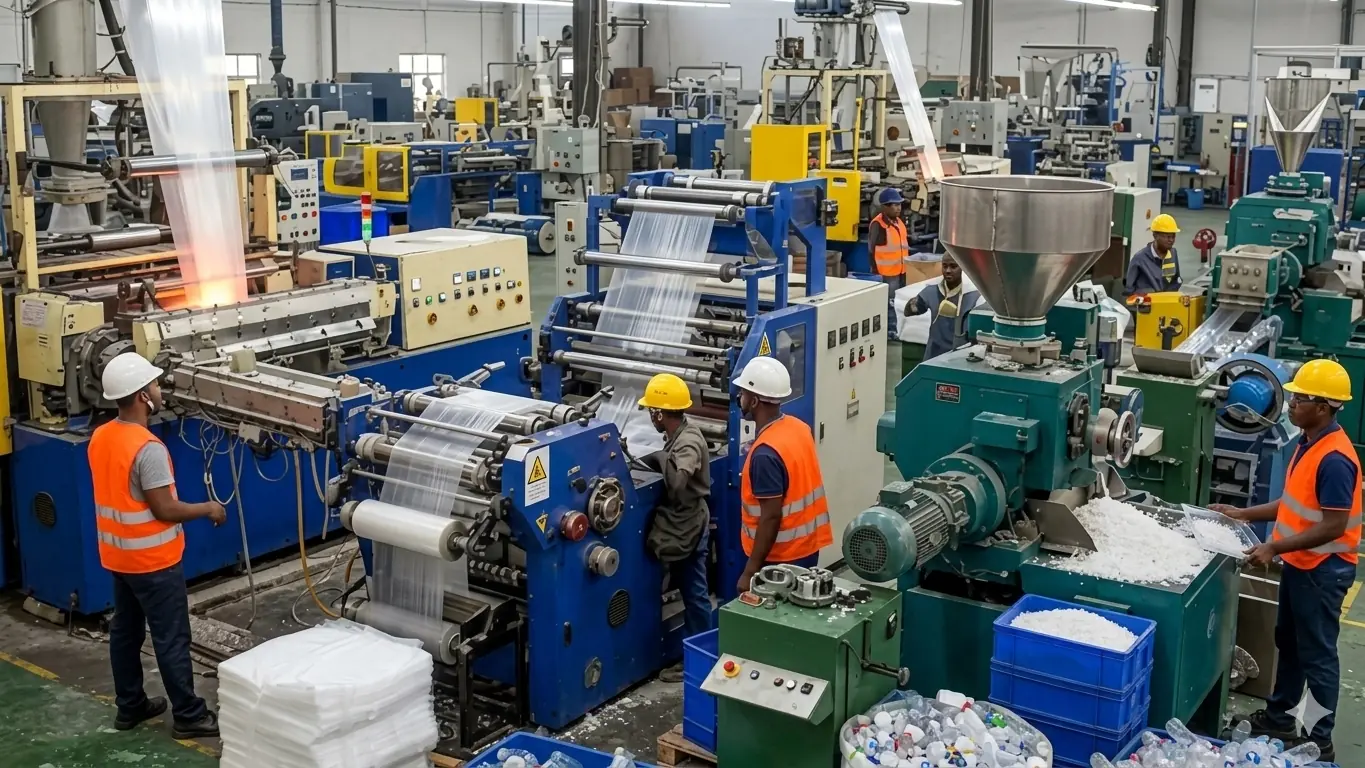
Business Investment: Can Cheaper Credit Support Expansion?
For manufacturers and other businesses, the importance of lower rates goes beyond the headline cost of a loan.
Cheaper financing can reduce the cost of working capital, inventory financing, and equipment purchases. It could also make projects that were previously too expensive to finance more viable.
But the transmission is unlikely to be immediate. Companies will still compare the cost of borrowing with expected returns from expansion.
The key question, therefore, is whether the lower policy rate eventually produces a meaningful decline in corporate borrowing costs rather than simply a lower benchmark rate.
-
Investor Allocation: Could Money Move Towards Equities?
Lower fixed-income yields can also change how investors allocate new money.
Nigeria’s equities market had already delivered a strong first-half performance, with the NGX All-Share Index gaining 46.8 percent by June 30. The index subsequently extended its gains, with the market’s July performance taking its year-to-date return to 57.62 percent.
A further decline in Treasury bill and bond yields could make equities relatively more attractive to some investors seeking higher returns. But that does not mean the rate cut automatically translates into a sustained stock-market rally.
Instead, investors will weigh lower fixed-income returns against company earnings, valuations, dividend prospects and the risks associated with equities.
The broader significance of the 23 percent MPR, therefore, lies less in the headline number itself than in its transmission. If banks reduce lending rates, credit expands, businesses increase investment, and fixed-income yields adjust lower, the cut could gradually feed into economic activity. If those transmission channels remain weak, the impact on borrowers and businesses could take much longer to materialise.
Ogochukwu Onwaeze is a writer specializing in business and economic journalism. At THEWILL News Media, she translates market trends, financial developments, and policy shifts into clear and engaging stories.